
904-463-2877
Judy@JudyHicks.com
12646 San Jose Blvd
Jacksonville, FL 32223
Allen Dye with North Star Mortgage Network talks to Judy about Mortgages
The key to a successful closing from the mortgage perspective is the upfront prep work that results in the lender’s underwriter having accurate and proper borrower documentation. Interest rates and program guidelines can change but the basics of getting a buyers mortgage approved remain a constant.
Prequalification is the first step. Before you even look at the first home you need to know what your buying power is. A lender or banker can pre-qualify you to a price range and payment. This helps us know what homes and neighborhoods to look at. Once you find your home, to submit an offer, we will need a pre-qualification or sometimes a pre-approval letter in hand. No seller will negotiate a contract without that document being submitted at the time of the offer. This will expedite the loan approval processes and will get you going in the right direction to make the home yours.
Use the handy mortgage calculator on this page to help you see what a possible mortgage payment would be. NOTE: The insurance and property taxes will not be included in the estimate.
Give Allen a call to discuss which program best suits your needs.
Mortgage Calculator

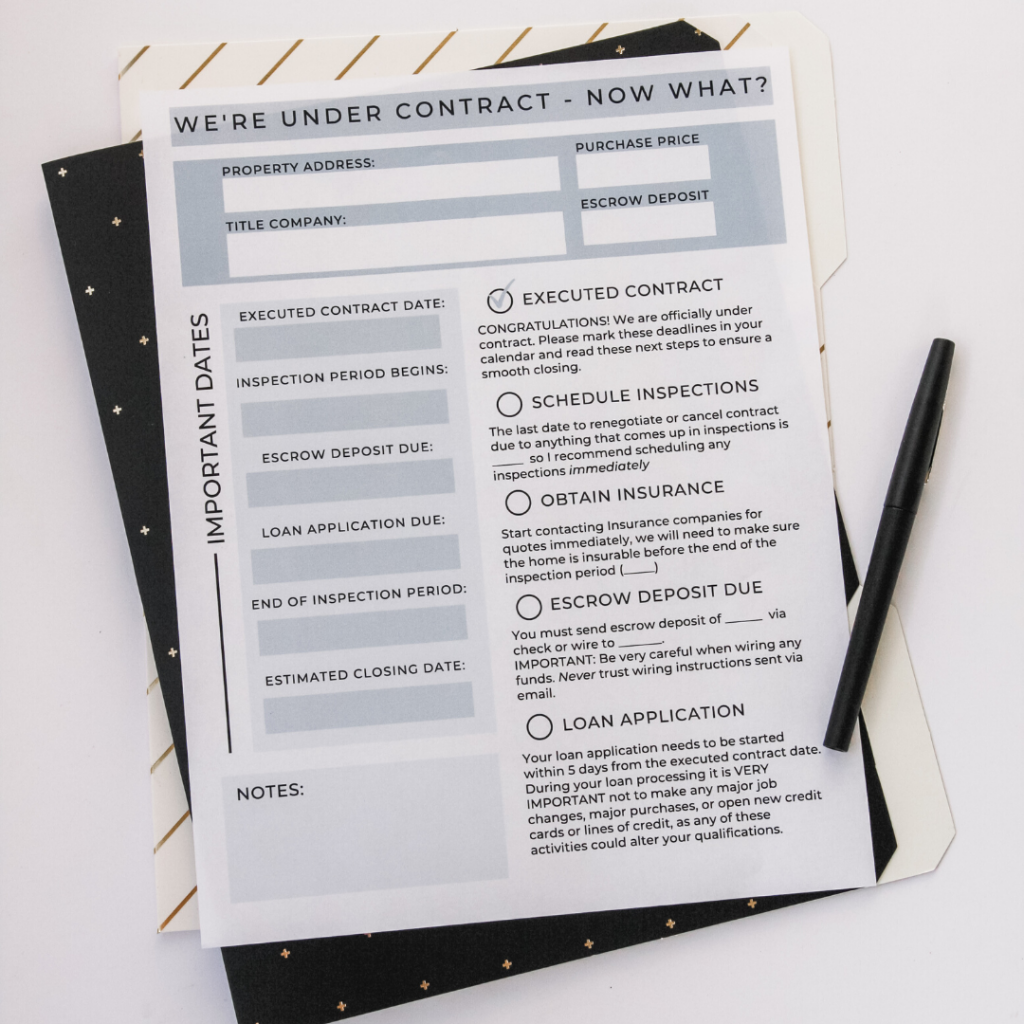
When choosing a loan professional, ask the following questions:
Once you find a loan professional you are ready to get pre-qualified.
Pre-qualification is the first step in getting a mortgage. Pre-qualification happens when a buyer discloses to a loan professional the amount of their income, the amount of their debt, and how much money they have to put down on a new home, to determine what their buying power is (how much money the loan officer thinks you can borrow for a home). This process also determines the type of financing you will receive (i.e.; conventional, FHA, or VA).
The approval process takes the buyer a step further. At this point the loan officer does a credit check to determine whether you are credit worthy (meaning is your credit score good enough for you to be financed). The loan professional validates your ability to purchase by collecting required documentation (i.e.; pay stub, bank statements, verification of employment, etc.).
Some buyers tend to wait for loan approval until after they have found a home. I discourage this. Your power as a buyer increases when you are able to make an offer with pre-qualification. By doing this, you let the seller know that you are capable and ready to buy their home. This is a huge benefit to the buyer and the seller.